The archive
The story files, by category
Every story on this site traces to court records, regulator files, federal data, or the named press coverage listed in its source ledger. Eight files are open, and more land each week.
The archive
Every story on this site traces to court records, regulator files, federal data, or the named press coverage listed in its source ledger. Eight files are open, and more land each week.
Documented policyholders betrayed by a clause, a word, or a technicality. Sourced from court opinions and regulator records.
The 15 January 2021 judgment is public, and so is the regulator’s published list of which wordings had to pay.
The receipts are 794 F.3d 457 and 580 U.S. 26. The Supreme Court’s question, decided December 6, 2016, was not about wind or water. It was about a broken seal.
The receipts are New York Attorney General releases from 2009. A separate class action settled at $350 million. No court ruled on liability.
The family raised the money and paid for the transplant themselves. The December 28, 1993 verdict was never the number that changed hands.
The charging document is public. It carries 34 more alleged counts from consumer complaints. State Farm denies any general practice of mishandling.
ProPublica clocked the review at 1.2 seconds a claim. Cigna says the process involves no algorithm at all. A federal judge read the plan language and let part of the case go forward.
A 21-word sentence in the standard homeowners policy decided what 65,380 slabbed households got paid. It took eleven years and a Supreme Court case to close the file.
A 2013 California law gives a policy owner 60 days and three warnings before a life policy can lapse. Whether it reaches a policy bought in Illinois and paid from California was set for an answer on April 16, 2025. The case settled first.
Federal auditors pulled one month of Medicare Advantage prior authorization data from the 19 largest plan companies and found 13,458 skilled nursing denials. Most were never appealed, and most of the appeals won.
The live national story of insurer retreat: pauses, non-renewals, last-resort plans, and rate hikes with traceable culprits.
The November 30 takeover release and the December 3 liquidation order, case 18CV-04739, put a 200-policy Butte County book against a $41 million hole.
The May 2023 pause never ended, and the fallback plan grew 44 percent in a year. A 29.1 percent FAIR Plan rate increase takes effect October 15.
After the January 2025 Los Angeles fires the California FAIR Plan assessed its member insurers $1 billion, and half of that is recoverable from ordinary policyholders under a line item called the Temporary Supplemental Fee.
Adjudicated insurance true crime. The retell always ends the same way: and they caught him.
Two Prudential policies and one from Metropolitan Life, held in 1933 on a homeless man who had no idea. Four of the buyers went to the electric chair.
A 2006 federal indictment on nine mail fraud counts each. An April 2008 Los Angeles jury. Two consecutive life terms apiece, July 15, 2008.
A former officer’s phone call to an analyst on 6 March 1973 cracked it open, and the Supreme Court later had to decide whether the analyst had broken the law.
The Greenwich evidence file holds a burning cabinet, an astrological chart asking whether he would go to prison, and a to-do list.
The NTSB file, the federal sentencing summary and the wire coverage put the jump, the motorcycle, the campground tent and both sentences on the record.
John Darwin vanished from the North Sea in a canoe in 2002. For most of the five years he was dead, he was on the other side of his widow’s bedroom wall.
A 2010 Rolls Royce Ghost, a 2015 Mercedes G63 AMG and a 2022 Mercedes E350 all met the same bear at Lake Arrowhead on January 28, 2024. A state wildlife biologist watched the videos and said it was clearly a human in a bear suit.
Documented people standing in a coverage gap when disaster arrived. The story’s moral is the paperwork itself.
The condo bylaws said every owner’s policy had to waive subrogation, and the tenant thought that waiver covered him too.
The 30-day wait is 44 CFR 61.11, and it is the smaller failure here. A standard homeowners policy excludes flood outright.
The document is a Minnesota Supreme Court opinion, No. A13-0124, affirming an appraisal award the insurer had refused to pay.
Two federal juries answered the same question in opposite directions, depending on which policy form bound each insurer. The Second Circuit upheld both in October 2006.
The documents are three 2019 Connecticut Supreme Court opinions and a state captive fund’s own pages. An estimated 35,000 homes sit in the zone.
Policyholders averaged $118,000 per claim. The uninsured averaged $4,400 in grants. Four weeks before the storm had a name, the 30-day waiting period had already drawn that line.
Protective Life ended the policy 31 days after the due date. Nine days before that date, a new California law had given him 60 days and required 30 days of written warning. It took eight years and the state Supreme Court to decide the law counted.
Verified absurd claims and impossible policies, always resolved to the actual clause that paid.
A local council fined a space agency for litter, the citation sat unpaid for three decades, and a radio audience finally settled it.
The slip’s conditions survive in a 1976 insurance journal paper. Twenty feet, undamaged, a museum’s word, a one-year window, and the underwriters keep the beast.
A Dallas firm sells the risk that somebody actually wins the prize. On February 4, 2015 the panel reopened a settlement signed almost nine years earlier.
The 2009 Lloyd’s announcement is the document. The century of body-part cover behind it is shorter on paperwork than the retellings suggest.
The museum floor dropped into a hidden cave with eight cars on it. By December, 251,258 people had bought tickets to look at the hole.
Westar 6 and Palapa B2 stalled in useless orbits in February 1984. The underwriters paid the claims, took title to the hardware, and spent $10.5 million sending a space shuttle to collect their own property.
History’s catastrophes and the insurance rules they created. Every strange line in a modern policy was written by a specific disaster.
Disasters That Wrote the Rulebook
EH.net counts 68 insurers bankrupted by Chicago and 32 more by Boston; the Encyclopedia of Chicago counts 58. Recovery ran 40 percent, then 70.
Disasters That Wrote the Rulebook
The policies covered fire and excluded earthquake. The earthquake started the fires. The market’s own history puts the settlement above $50 million.
Disasters That Wrote the Rulebook
The carrier paid $60,000 more than the fire cost, per PBS. A jury acquitted both men on December 27, 1911. New York’s compensation law paid from July 1, 1914.
Disasters That Wrote the Rulebook
The building did not burn down. Locked and inward-opening doors did the killing, and a hardware salesman who had meant to be in the audience designed the bar that opens them.
Disasters That Wrote the Rulebook
13,200 houses, 87 churches, and not one policy to claim on. The strange lines in your homeowner policy were written in that ash.
Disasters That Wrote the Rulebook
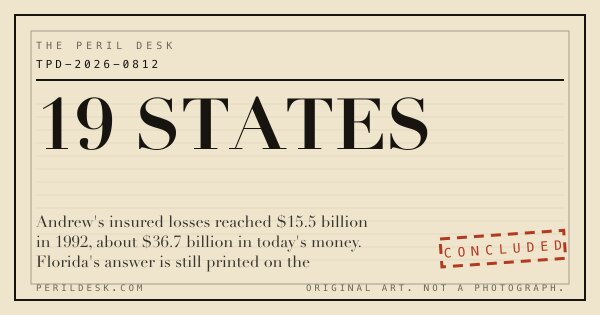
Andrew’s insured losses reached $15.5 billion in 1992, about $36.7 billion in today’s money. Florida’s answer is still printed on the declarations page in 18-point boldface.
Government and insurer datasets turned into rankings, odds, and records. Find your state, check the denominator.
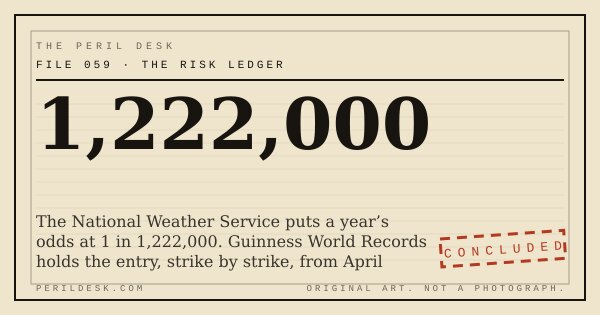
The National Weather Service puts a year’s odds at 1 in 1,222,000. Guinness World Records holds the entry, strike by strike, from April 1942 to June 1977.
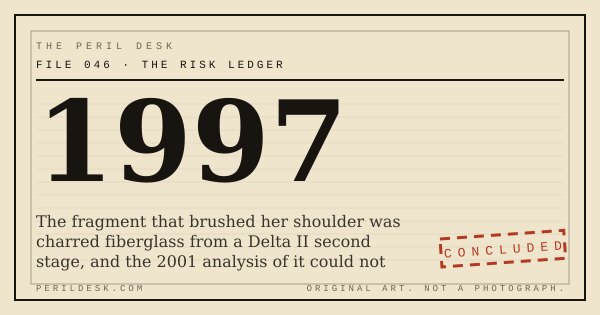
The fragment that brushed her shoulder was charred fiberglass from a Delta II second stage, and the 2001 analysis of it could not positively identify the piece.
State Farm’s newest study puts national odds at 1 in 139, with a 24-fold spread between West Virginia and Nevada. Find your state in the table.
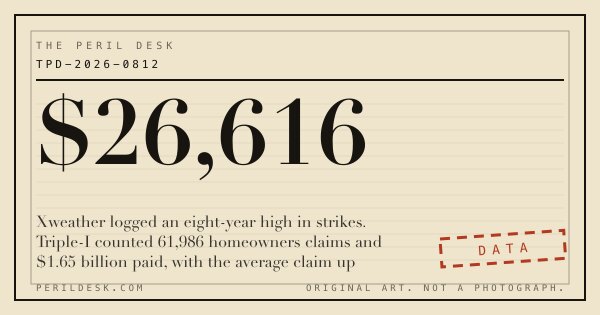
Xweather logged an eight-year high in strikes. Triple-I counted 61,986 homeowners claims and $1.65 billion paid, with the average claim up 42.8 percent in a single year and 146.9 percent since 2017.
Pets and wildlife colliding with the insurance system, one docket at a time.
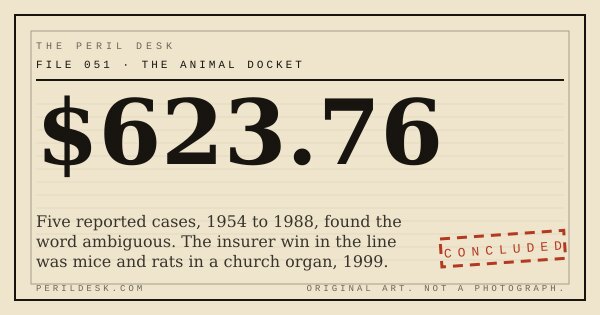
Five reported cases, 1954 to 1988, found the word ambiguous. The insurer win in the line was mice and rats in a church organ, 1999.
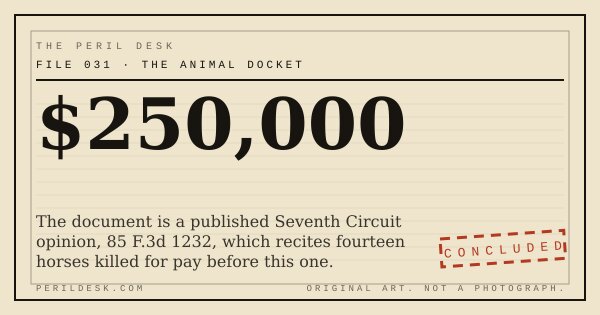
The document is a published Seventh Circuit opinion, 85 F.3d 1232, which recites fourteen horses killed for pay before this one.
DNA tied at least 21 South Lake Tahoe break-ins to bear 64F. The splintered doors ran through the same homeowners policies that handle fire and hail.
Medical bills, the machinery that decides who pays them, and the paperwork nobody is shown.
The receipts are GAO-19-292 and a federal statute in force since 2022. About 20,700 insured flights, two thirds outside the network, and a median charge up 60 percent in five years.
Vox published the billing records on January 7, 2019. The hospital stopped the practice on February 1 and rewrote its policy in April.
A father posted the receipt in 2016 and the internet priced the wrong thing. The on-record answer names a second person in the room.
Vox and Kaiser Health News published the itemized statement in 2018. The same reporting found the same fee running from $1,112 to $50,659, and the hospital waived it after publication.
The No Surprises Act handed the fight to a private arbitrator the patient never meets. On July 22 their names became public, and the provider win rates run from 51 to 96 percent.
The No Surprises Act banned balance billing for emergency rooms and for air ambulances. Congress left ground ambulances out, and four line items on one San Francisco hospital transfer show what that exclusion is worth. KFF Health News published the itemized bill on February 28, 2025.
The models, scores and algorithms that price a policy before a human ever reads the file.
The November 2023 filing alleges reversals above 90 percent and appeals near 0.2 percent. UnitedHealth denies the claims.
Sworn testimony from October 13, 2016, a commissioner’s February 2018 investigation, and the company’s on-the-record denial that the deposition was fairly read.
The Missouri fines passed $7 million. The Florida order came January 16, 2008, and 150,000 pages went online April 4. Allstate called the criticism out of context.
The printed hearing record, CHRG-111hhrg73743, counts almost 20,000 rescissions in five years and keeps all three answers, one of them “I would not commit to that.”
HB25-1182 made the wildfire model behind a premium a disclosable number, but the regulation telling insurers when to actually send it does not bind until October 1.
The image that decides whether a homeowners policy survives is taken from the air, and Colorado’s own bulletin on the practice says a bulletin binds nobody.
Insurance written on human lives, and the paper the arrangements left behind.
Graunt’s 1662 Observations survives in facsimile. The survivor table under every life policy traces to a shopkeeper adding up old death sheets.
The documents are a May 2004 SEC emergency action and an August 2014 federal sentencing in the Southern District of Florida.
The statute, the Department of Insurance report to the Legislature, and the carrier filings are all public documents, and the registry lists people by name.
One event, reconstructed minute by minute from the official record.
Her class covered tsunamis the term before. On December 26, 2004, the tide rushed out and bubbled, and she told her mother to leave.
Life magazine logged the reasons one by one on March 27, 1950. A soiled dress, a catnap, an unfinished letter, a geometry problem, a stalled car.
Guinness records the severed cables piling into a spring-like spiral under her car. The fire was out in 40 minutes and the building opened Monday.
These pages carry flat-fee partner links, disclosed on the page. Every partner pays the same flat fee, so no link earns more than any other.
Eight of the largest US home insurers, ordered on the 2026 claims study from J.D. Power, with AM Best financial strength and NAIC market data alongside.
Eight renters carriers, scored on the 2025 J.D. Power study, with the study average marked on every row.
Eight life carriers, with 2025 scores from J.D. Power, AM Best ratings, and NAIC complaint indexes, all sourced on the page.